Treasury's Stablecoin Rule Closes October 19. One Question In It Is Aimed at Credit Unions.
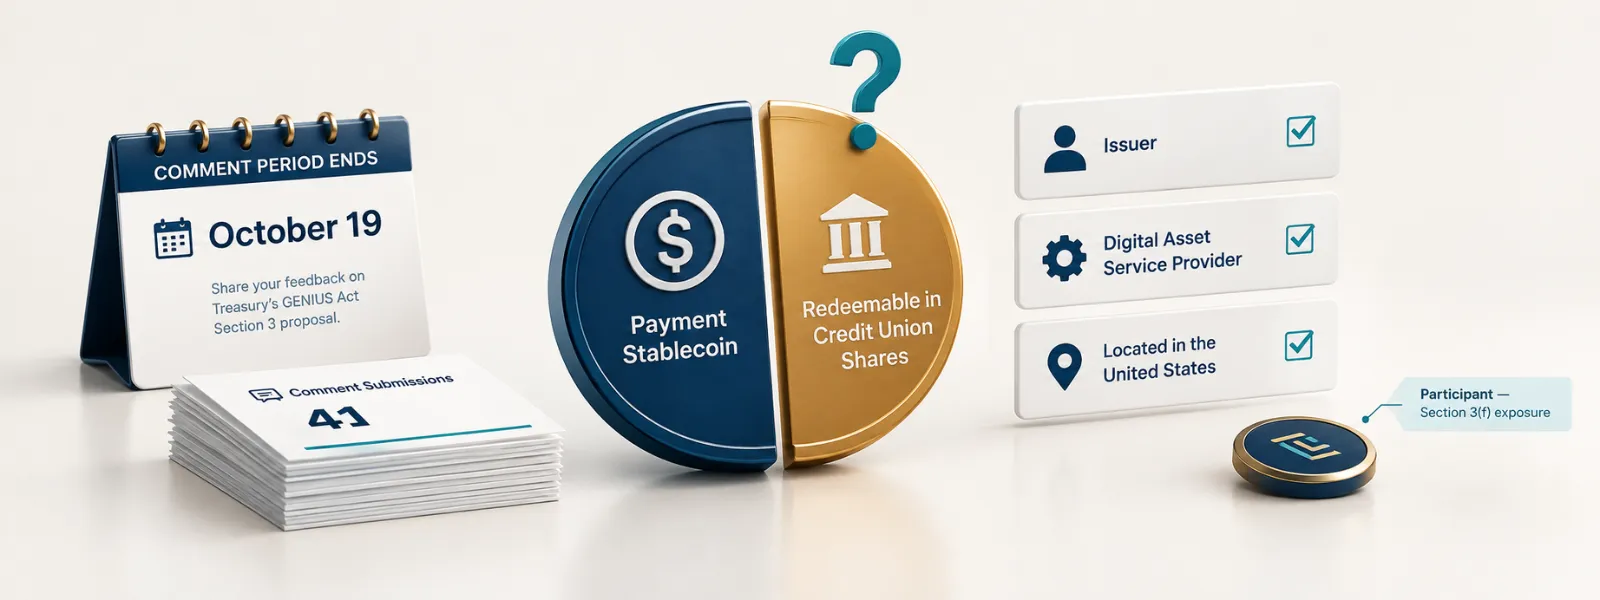
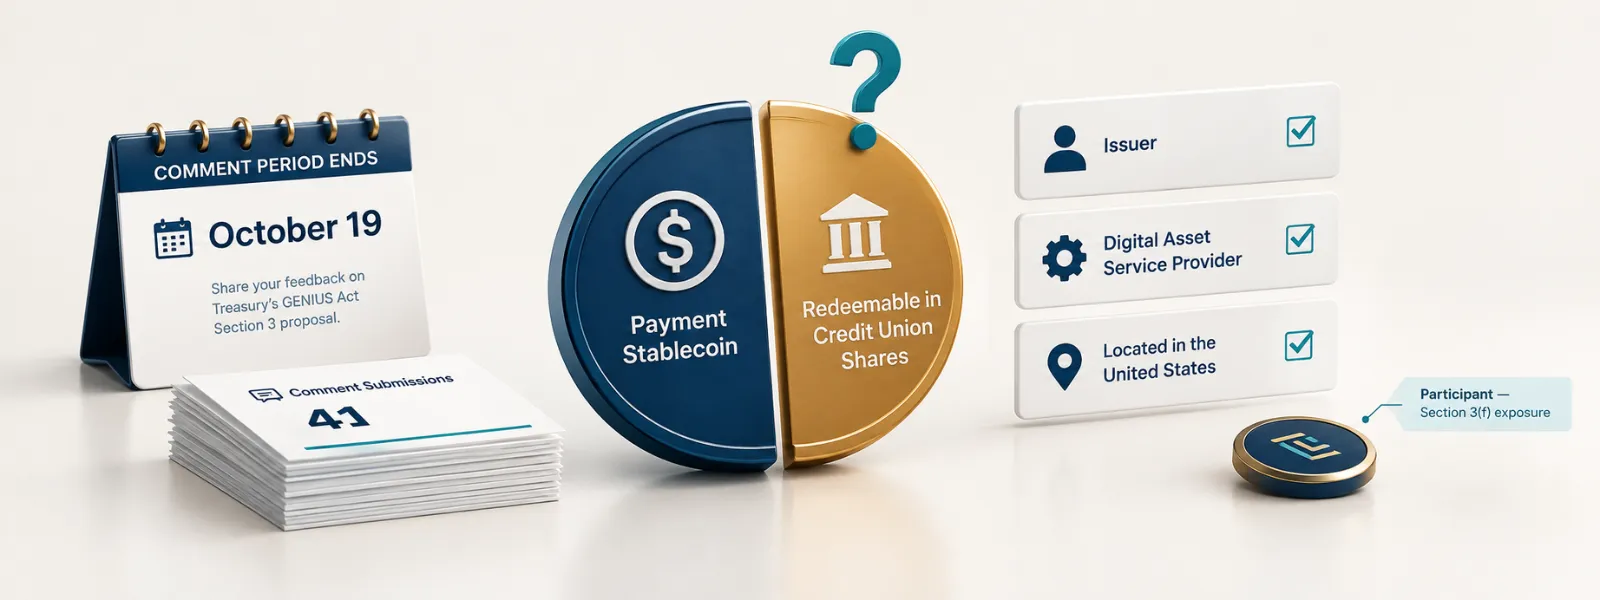
Treasury published its proposed rule implementing section 3 of the GENIUS Act on August 18, 2026, at 91 FR 53368. Comments close October 19. As of late September, 41 had been filed.
Nothing in it is in effect. Treasury describes January 18, 2027 as the Act's expected effective date, which is the 18-month mark after enactment; the Act can also take effect 120 days after the primary federal payment stablecoin regulators issue final regulations, whichever comes first. The central offer and sale prohibition does not bite until July 18, 2028.
The reason to read it now is that the proposal decides who counts as an issuer, who counts as a digital asset service provider, and where a person is located. Those three definitions determine whether any of this reaches you, and Treasury is asking for comment on all three.
What the rule would actually do
The proposal would add a new Part 1523 to title 12 of the CFR. It implements section 3 of the Act, codified at 12 U.S.C. 5902, which sets out three prohibitions on different clocks.
Section 3(a) makes it unlawful for anyone other than a permitted payment stablecoin issuer to issue a payment stablecoin in the United States. Treasury reads the Act to also allow foreign issuers that meet the section 18(a) criteria, which include a Treasury comparability determination for the home regime and registration with the OCC.
Section 3(b)(2) applies from the Act's effective date. It makes it unlawful for a digital asset service provider to offer, sell, or otherwise make available in the United States a stablecoin from a foreign issuer, unless that issuer has the technological capability to comply with lawful orders and reciprocal arrangements, and will comply.
Section 3(b)(1) applies from July 18, 2028. From that date a digital asset service provider may not offer or sell a payment stablecoin to a person in the United States unless a permitted issuer produced it.
Section 3(f) carries the penalty. Knowing participation in a violation of section 3(a) draws a fine of up to $1 million per violation, up to five years imprisonment, or both.
Three readings that widen who is covered
Issuers are also digital asset service providers. Treasury considered treating the two categories as mutually exclusive and concluded the better reading is that they overlap. Anyone who, for compensation or profit, engages in the business of issuing payment stablecoins in the United States is a digital asset service provider. Both sets of prohibitions then apply to the same entity. Treasury's stated reason is that the opposite reading would let an issuer offer and sell coins a plain exchange could not.
White label branding creates exposure without making you the issuer. The proposal defines an issuer by two functions: the obligation to convert, redeem, or repurchase for a fixed amount of monetary value, and representing that it will maintain a stable value. A party that supplies only its branding is not the issuer under that test. Proposed section 1523.2(d)(2) then says a person participates in a violation by coordinating with the issuer to facilitate key steps, and Treasury names the branding party in a white label arrangement as an example.
Location turns on facts you may not collect today. For an individual, located in the United States means physically present, unless the person is a non-resident who is only temporarily here. A U.S. resident travelling abroad is outside the definition. For an entity it is organized or incorporated under U.S. or state law, or principal place of business in the United States.
If you are considering a branded stablecoin product where someone else holds the redemption obligation, read proposed section 1523.2(d) before you read anything else. Treasury's position is that you would not be the issuer and could still face the section 3(f) criminal penalty as a participant. Those two conclusions sit in the same rule, and the branding arrangement is the example Treasury chose to illustrate the second.
The question aimed at credit unions
Question 5 in the NPRM asks whether the term payment stablecoin should reach a digital asset that the issuer must redeem in something functionally equivalent to the monetary value the Act enumerates, meaning national currencies or deposits as defined in the Federal Deposit Insurance Act.
Treasury then gives its own example: a digital asset "redeemable only in credit union shares." It asks whether the routine convertibility of credit union shares and bank deposits in the U.S. financial system bears on the answer, and what evasion risk each possible reading creates.
That is a scope question with a direct answer only credit unions can supply. If Treasury reads the term broadly, a share-redeemable token issued by or for a credit union falls inside section 3 and its criminal penalty. If it reads the term narrowly, that product sits outside the framework entirely. Treasury has not decided, which is why it asked.
The comment file is small. Forty one comments on a rule of this reach means a well documented submission from an operator carries weight that it would not carry in a docket of four hundred.
What to do before October 19
Decide whether you are in the definitions, and write down why. Three tests matter: are you an issuer under the two-function test, are you a digital asset service provider, and are you or your customers located in the United States under the proposed definition. Date the memo. If the final rule moves a definition, you rerun one analysis instead of starting cold.
If a stablecoin product is anywhere in your roadmap, map the parties. Who holds the redemption obligation, who makes the stable value representation, who supplies the branding, who mints, who makes markets at launch. Proposed section 1523.2(d) assigns exposure by function, not by contract label. Two of its three examples describe activity a partner performs rather than the issuer.
Treat the foreign issuer safe harbor as a controls requirement. Proposed section 1523.2(c) protects a non-U.S. issuer that reasonably believes recipients are outside the United States, but only where policies, procedures, and controls are adopted, actually implemented in operations, and periodically reviewed as conditions change. Treasury says static controls are not reasonably designed. That is a familiar standard to anyone who has been examined.
Read the alternatives before you assume the safe harbor survives. Treasury describes an alternative that would make issuance to a U.S. person unlawful regardless of diligence, narrowing or removing that safe harbor, with knowledge relevant only to whether criminal penalties attach. A second alternative would borrow the offshore transaction framework from Regulation S. Both are live.
Comment if Question 5 describes you. Treasury asked a specific question about credit union shares and gave a reason for asking. An operator explaining how share redemption works in practice is answering a question the agency posed to itself.
Source note
This article is based on the Treasury NPRM, GENIUS Act Regulations on Payment Stablecoin Issuance, Offer, and Sale, 91 FR 53368, published August 18, 2026, docket TREAS-DO-2026-0496, RIN 1505-AC95; the GENIUS Act as codified at 12 U.S.C. 5901, 5902, 5903, 5904, and 5916; and Treasury's August 17, 2026 press release. Scope, definitions, penalties, and safe harbors described here come from a proposed rule that has not been finalized.
Disclaimer
This article is provided for general information and does not constitute legal advice. Regulatory requirements, compliance dates, examiner priorities, and enforcement posture change frequently. This rulemaking is open and unresolved, the provisions described here reflect a proposal rather than a final rule, and section 3 carries criminal penalties. Verify current requirements against primary agency sources and your legal counsel before acting on anything described here.